Ever thought deeply about the typical financial counsel African parents, even your father, bless his soul, pass down to their children when they are coming of age? “Son, I’m giving you a good education from good schools. After graduating, you’ll have to work hard; don’t look at my wealth because it’s mine and your mother’s. I too started from nothing, ahem ahem… so learn a skill on which you will build something for your family too. Start small. I could perhaps give you some capital to err…start a small business of your wish.” Then on they go: “We expect you to take care of us when we grow old,” and so forth. Sounds familiar?
Because this has been repeated so many times into our African ears, this mindset appears so ‘right’ that we grow up trying to ‘make mzee proud by being a real man who worked his own way up the ladder to become something.’ That, however, is a very dysfunctional approach to finances, and it validates the proverb “a fool (or a fool’s family) and his money will soon part” Hell, it will take you on all those Tom Sawyer adventures, but that’s it. It won’t keep your wealth intact beyond your lifespan. Because, hey, how can you keep the wealth you work so hard for, when the very people who should perpetuate it, namely your offspring, have been made to feel like they are some parasites that need to be DOOMed as soon as they clock 18. No wonder when kids hit the second floor, African parents start feeling a selfish type of way, acting all protective of family wealth. Why? No one has taught African parents something called Old Money.
See, there is a quiet difference between Wealthy people and families who have had money for centuries and show no single sign of losing it. There is a behavioural difference between someone who grew up around money and one who just got it. One looks loud; the other boring and basic. Guess which one is still standing after three historical world recessions and serious global economic disruptions? The boring, and that is Old Money, baby!
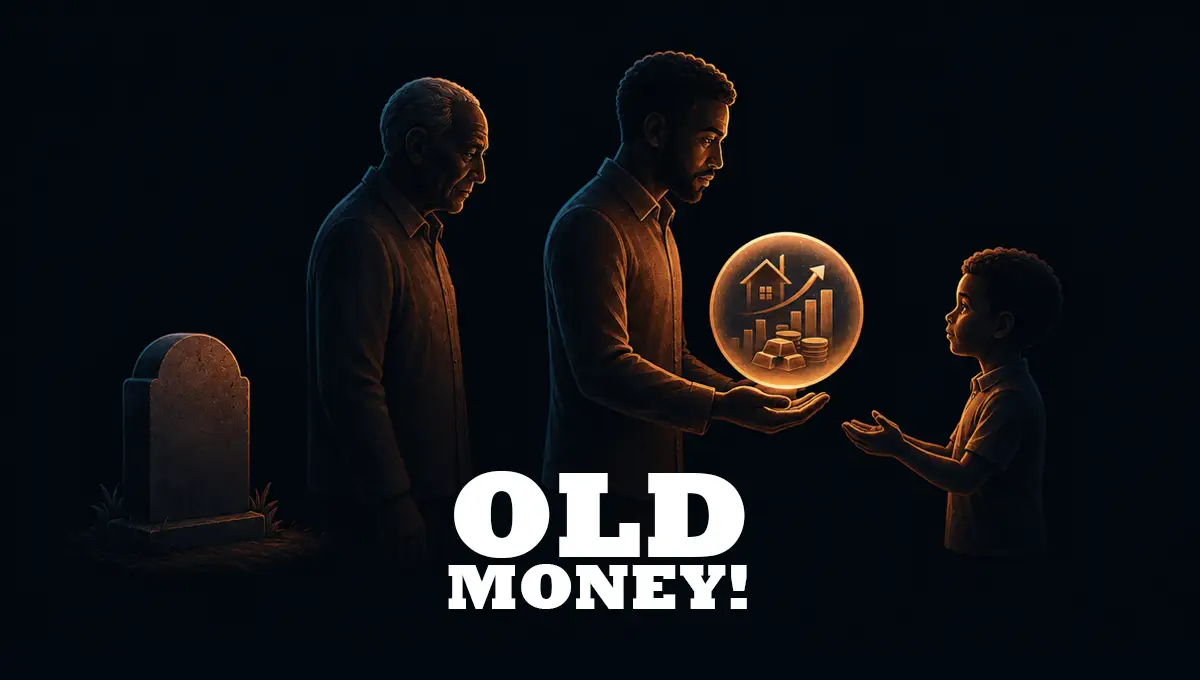
Old Money is not old Pablo-Escobar bills that have been around for so long that rats are nibbling on them. No! Old Money is wealth that moves through a family like a river (it moves down from Great-granny to Granny to Father to Son), not like rain. For rain comes hard, soaks everyone and their mother, and is gone by Tuesday. A river has banks, channels, and even people who know how to clean off hyacinth. Families with Old Money did three things early: they owned assets, not just a good home and cars. They separated spending from identity. And they handed the money and wealth to their children, and, no, they didn’t hand it to fools; they taught them how to grow it into bigger money.
Think of the Rockefellers (some stinking-rich chaps in the States); they started in oil, banking, and trade, then they moved cash into land, companies and trusts/bonds. The founders got rich; educated their children on how to grow the wealth, venturing into modern businesses like hotels, real estate, tech, etc, and not chasing random degrees to become doctors or engineers.
By the time you meet a 25-year-old from that line, they are not ‘figuring out life’ or ‘using dad’s connections for a government job. No. They are joining a board, managing a foundation or studying how to steward capital. For the Rockefellers, money didn’t start at zero; someone in 1920 decided it wouldn’t.
How Old Money Is Made
Again, don’t mistake Old Money families with Wealthy families. Sudhir and Ham’s strong businesses, striking homes, Bentleys, and Range Rovers aren’t necessarily Old Money. We can’t predict if their wealth will still be here 100 years after they die. What could qualify them as Old Money is what they teach their children about this wealth, and if their wealth is not tied to them as individuals. Old Money folks do this:
#1. They buy assets that compound: Land in prime areas, shares/stocks/bonds in productive and highly insured businesses (government bonds are a rare treasure), buildings that collect rent. They spend on income, not on principal.
#2. They use structures: Family trusts, holdings companies, and family constitutions. This sounds boring because, yes, it is boring. But boring protects money from emotional decisions.
#3. Delayed gratification: The rule is ‘we don’t eat the seed.’ You can enjoy the harvest, but you have to replant. So you won’t be seeing them with the latest iPhone if it’s not directly generating an income. They do not need to market themselves with expensive stuff because their target market does not rely on impressions. They buy stuff that lasts years (if you’ve been to a home with very old but strong authentic-looking furniture UKWIM), and try to avoid things that are expensive in the long run (i.e. the retail price of a TV set is not its actual price, it’s the retail price + other expenses that come with it, e.g. monthly subscription, electricity, repairs, stress/depression/health damages related to broadcasted information.
#4. They educate for stewardship, not salary or independence: Children learn a lot about balance sheets, taxes, and risk before they learn about cars or fashion. They are not educating their kids to start their own thing. Their children are in the room when deals are made and are being groomed to take over.
Money doesn’t disappear because people are lazy; it disappears because wrong beliefs are passed down to children:
#1. “When you grow up, you’ll have to go and figure out on your own” This only means that every generation has to start from zero, make all the mistakes that come from starting from zero, and burn 20 years learning what the previous generation could have taught in 2. Old Money families do not cut off kids at 18; they in-board them, no room for trial and error. Make the mistakes while you are young; by 18, you are ready.
#2. Old Money families barely throw heavy weddings, fundraiser dinners, house-warming parties, and baby showers. This is for those who want to show off, the middle class and the wealthy.
#3. A cousin or uncle calls with a school fees emergency and has no plan to repay; Old Money families do not flow with that kind of generosity. Yet they have hands in charity foundations and Rotary clubs because that is where they cut deals with the high and mighty. Note: for them, every act of generosity is intentional and only meant to create leverage for wealth creation and protection.
Old Money vs. New Money
This is the face of new money: A man builds a fast-growing business in telecom, real estate or imports; cash flow is strong, the lifestyle is visible, his home is a mansion, and his car number plates are customised. But if the business is founder-dependent, if there is no trust structure, no succession plan, and he is training his children to be self-reliant and not tap into his sweat, that wealth is one generation deep. That’s not an insult, it’s economics: wealth without institutions functional into the unforeseeable future reverts to the mean.
And this is Old Money, right here: A man acquires land/property, incorporates and keeps it within family structures. You see his children’s names tied to tea, coffee, and real estate holdings, simultaneously creating structures that help the business survive political and economic cycles. His properties are held under a family company rather than in individual names. That means his children cannot sell them as personal assets because they belong to the company. This structure helps protect the properties from internal disputes, unauthorised sales, and external claims. It’s a smart way to preserve family wealth for generations.
Build Generational Wealth (Old Money) Now
You do not need a strong surname or an inheritance. Create one and operate it through a system
#1. For every shilling earned, 10% buys an asset first.
#2. Plan a family you build wealth with, not children you pressure into supporting you later. Structure your life so you do not depend on them in old age. You are the parent; responsibility for bringing them into the world sits with you, not the other way round. Children do not owe you for being born, so plan for their future instead of shifting financial expectations onto them. Wealth grows better when each generation builds without being burdened by the previous one.
#3. Separate identity from spending: You are not your car, phone or outfit. You are your balance sheet. Do not post your wealth; let others showcase your business while you stay private.
#4. Build structures early: write simple rules: ‘We do not sell property to fund lifestyle. We borrow against it or rent it. We do not give free money to relatives. We lend them or pay them a wage for work.’
#5. Teach the next one: Train your children to perpetuate your wealth, not to walk away from it.
#6. Think 25-year blocks, not trends.
Ask, will this matter in 2070? Do not build things that will last or matter only in your lifetime. Compiled by Mwesigwa Joshua